Fieldwork conducted on 4 - 7 August
2026
According to BRC-Opinium data, consumer expectations
over the next three months of:
-
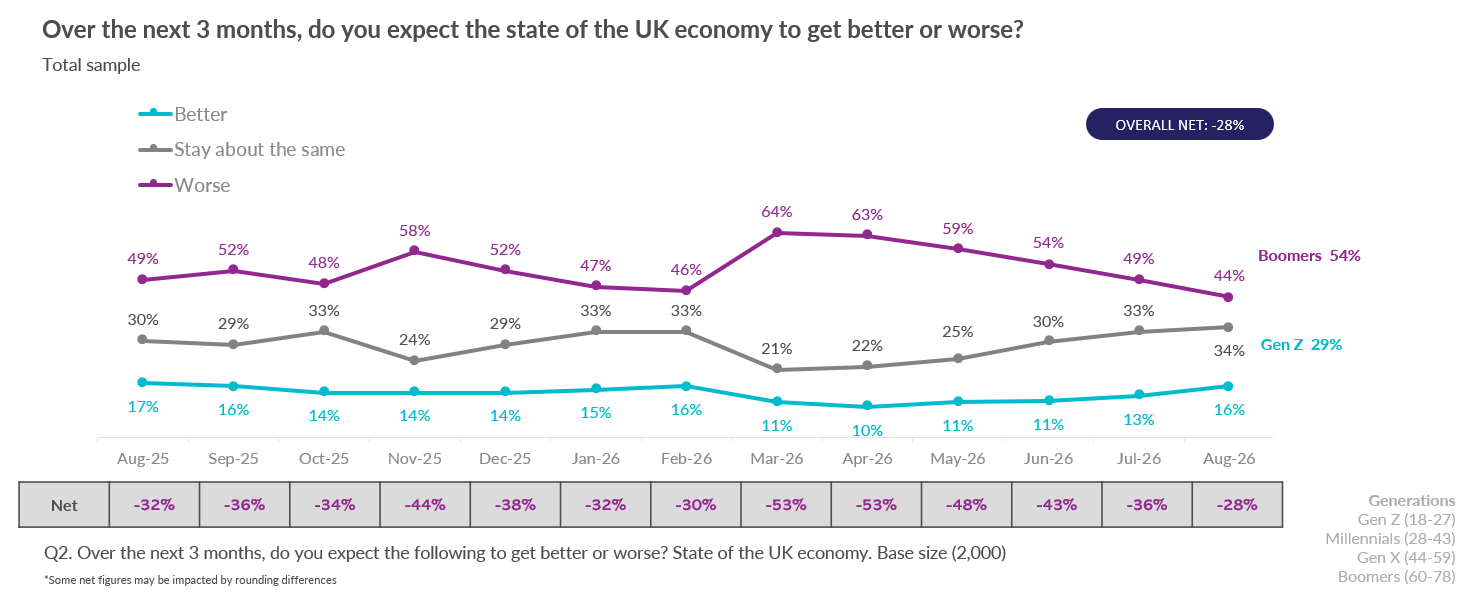
The state of the economy improved to -28 in
August, up from -36 in July.
-
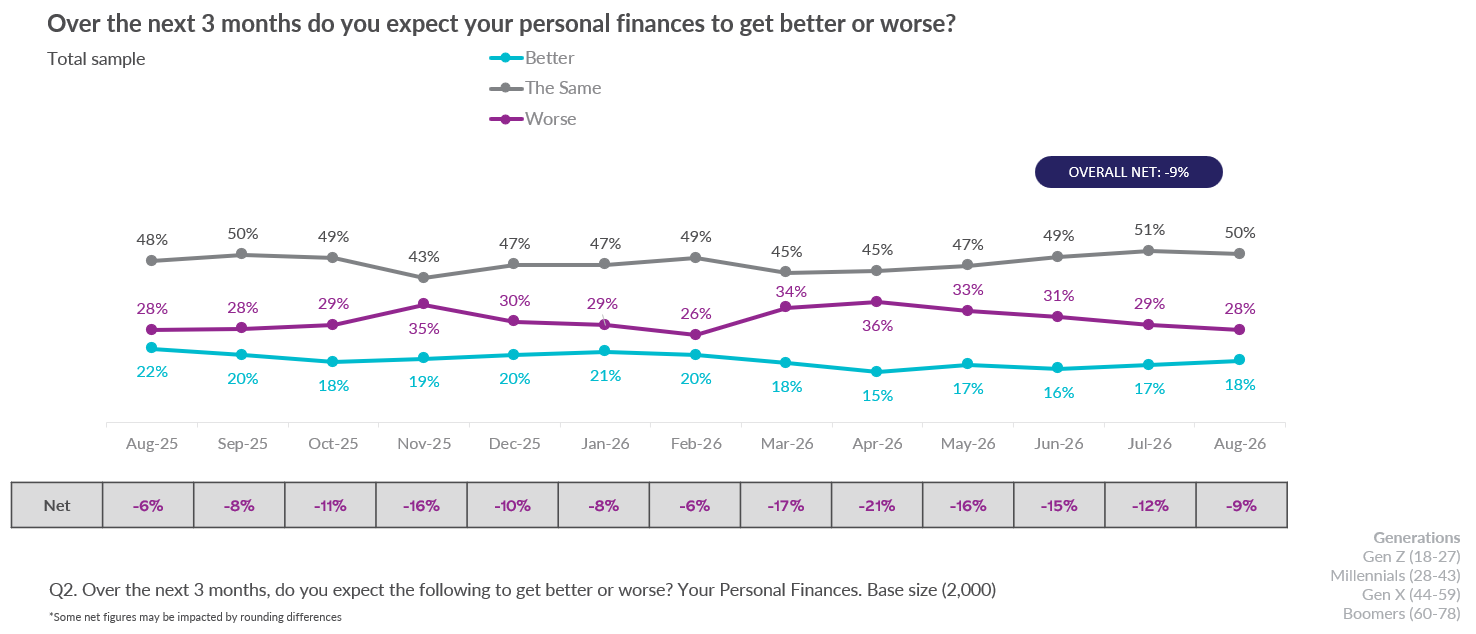
Their personal financial situation improved to
-9 in August, up from -12 in July.
-
Their personal spending on retail rose to +8
in August, up from +1 in July.
-
Their personal spending overall increased
slightly to +15 in August, up from +13 in July.
-
Their personal saving fell slightly to -5 in
August, from -4 in July.
Helen Dickinson, Chief Executive of the British Retail
Consortium, said:
Consumer sentiment continued to rise with confidence in the
economy hitting its highest level since the historical lows
reached at the start of the Iran conflict. Expectations for
personal finances saw a small improvement, driven by an
optimistic Gen Z. This same generation also reported a bump in
spending plans, as the stifling summer heatwaves are expected to
give way to more shopping-friendly temperatures in much of the
country.
The administration is enjoying a
honeymoon boost driven by less pessimism about the outlook, but
maintaining that momentum will depend on whether the Government
can ease the pressure on household budgets. Retailers compete
fiercely to keep the cost of food and essentials down, yet
mounting regulatory and tax burdens risk pushing prices higher.
The Budget will be the acid test of this government's real
commitment to growth: if the government can reduce retail
business costs, from energy bills to business rates, it will be
ordinary households who feel the benefit. A Budget that backs
retail and reduces costs is a pro-consumer Budget.
Consumer expectations for the state of the economy
over the next three months:
Consumer expectations for their personal financial
situation over the next three months:
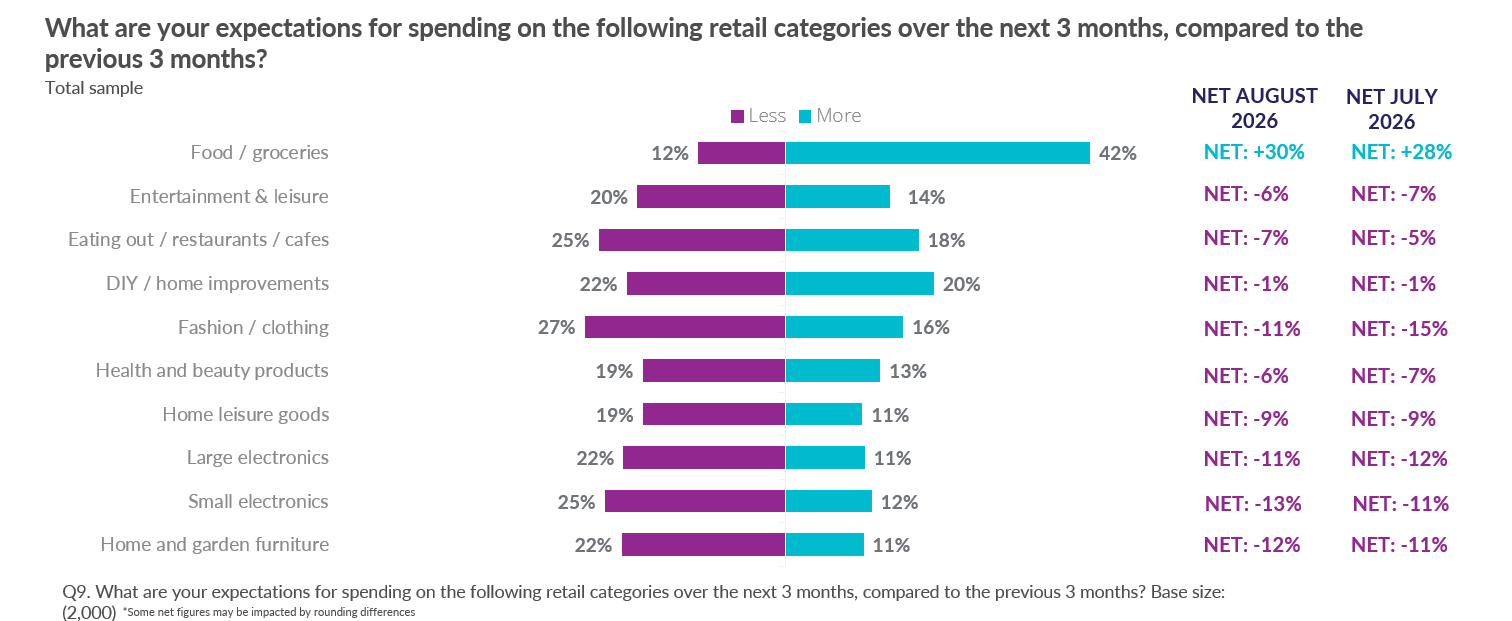
Consumer expectations of spending over the next three
months by category:
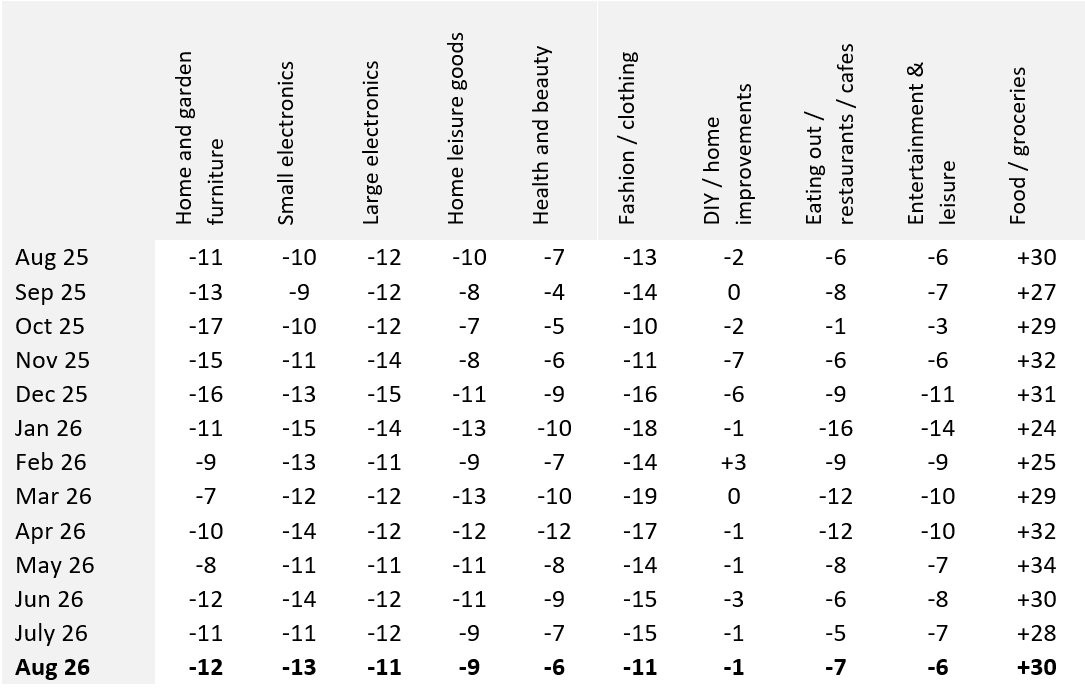
Consumer NET expectations of spending over the next
three months by category:
-ENDS-
The BRC sent this release to our "Monitors" and "General
Retail" media list. To check/update what media lists you are on,
please contact us below.
Methodology:
Fieldwork conducted by Opinium for the BRC. Sample included 2,000
UK adults and results have been weighted and assigned a net
score. The better/worse figures in the graphs are rounded, while
net scores are calculated from precise figures. Questions were:
- Over the next 3 months, do you expect your personal finances
to get better or worse?
- Over the next 3 months, do you expect the state of the UK
economy to get better or worse?
- What do you plan to do in relation to your spending over the
next 3 months?
- Reflecting on your retail spend across different categories,
overall do you expect to spend more or less on retail items over
the next 3 months?
- What are your expectations for saving over the next 3 months?
- What are your expectations for spending on the following
retail categories over the next three months compared to the
previous 3 months?
If you would like the results of the questions by Gender,
Generation, Location, Working status, or Income, please contact
the Press Office. Generations are defined as: Gen Z (18-29),
Millennial (30-45), Gen X (46-61), Boomer (62-80).
This monitor was started in March 2024, and records are from this
date.
