Covering the four weeks 02 - 29 August 2026
According to BRC-Sensormatic data:
-
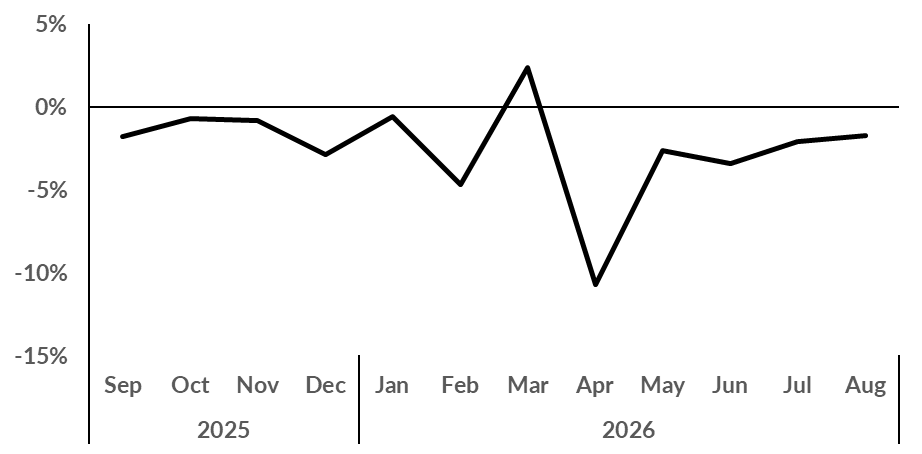
Total UK footfall decreased by 1.7% in August
(YoY), up from -2.1% in July.
-
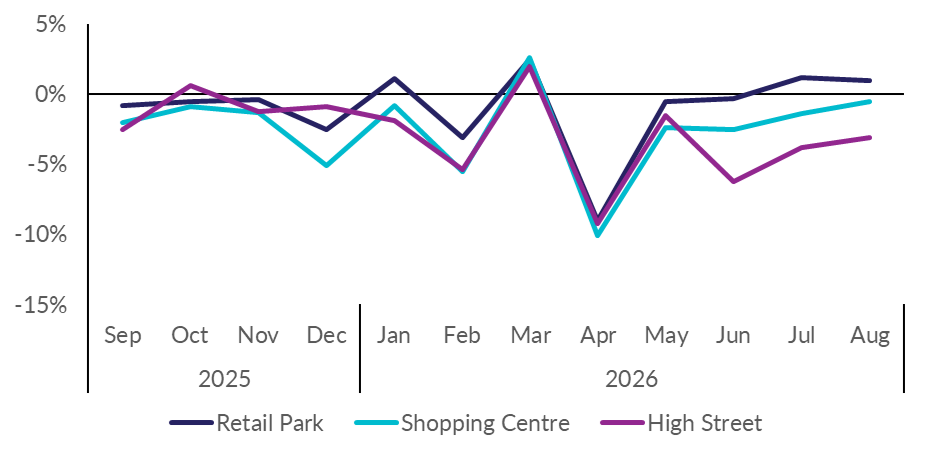
High Street footfall decreased by 3.1% in
August (YoY), up from -3.8% in July.
-
Retail Park footfall increased by 1.0% in
August (YoY), down slightly from 1.2% in July.
-
Shopping Centre footfall decreased by 0.5% in
August (YoY), up from -1.4% in July.
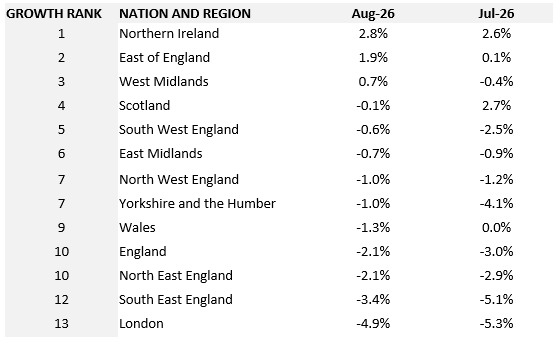
- Footfall decreased by 0.1% (YoY) in
Scotland, 1.3% in Wales, and by
2.1% in England, and increased by 2.8% in
Northern Ireland.
Helen Dickinson, Chief Executive of the British Retail
Consortium, said:
Footfall improved on the previous month, though still down on
last year. The cooler temperatures played a key role, bringing
shoppers back after a scorching July to stock up on essentials
and back-to-school items. Retail parks were the standout
performers but the overall picture shows high streets face an
uphill battle.
Retailers don't need warm words, they need lower costs. With his
first Budget weeks away, Chancellor Healey has a chance to throw
Britain's high streets a lifeline. Retail faces cost pressures
and households are watching every penny. Government action on
business rates and energy costs would help keep prices down,
support investment, and sustain the jobs and communities that
retail underpins across the country.
Andy Sumpter, Head of Consulting & Analytics - EMEA
for Sensormatic, said:
August delivered a modest improvement for UK retail footfall,
with total visits down -1.7% year-on-year. While still firmly in
negative territory, this marks a welcome improvement on both July
and June, suggesting the pace of decline may be beginning to
ease. However, it is worth remembering that this remains negative
growth against last year's already modest performance,
underlining the continued pressure facing retailers.
This performance was once again driven by Retail Parks, which
recorded growth of +1.0%, making them the only retail destination
to attract more visitors than a year ago. High Streets remained
under the greatest pressure at -3.1%, while Shopping Centres were
comparatively resilient at -0.5%. Above-average temperatures may
have continued to influence behaviour, although conditions were
less extreme than July's record-breaking heat. Meanwhile, rising
inflation, now at a two-year high, is likely placing renewed
pressure on disposable incomes.
With the industry's most important trading period fast
approaching, there are reasons for cautious encouragement, but
not complacency. England continues to lag the other home nations,
weighing on the overall UK result. The challenge for retailers
remains unchanged: converting a modest improvement in footfall
into meaningful spend as the industry's most important trading
season draws nearer.
MONTHLY TOTAL UK RETAIL FOOTFALL (% CHANGE YOY)
UK FOOTFALL BY LOCATION (% CHANGE YOY)
TOTAL FOOTFALL BY NATION AND REGION
-ENDS-
2026 Monitor dates can be found here: Insight
Calendar
Methodology:
All figures are calculated using precise shopper numbers entering
retail stores across the UK, whichever destination they are
located.
While High Streets, Shopping Centres and Retail Parks are the
main components of the Total Footfall, there are also additional
categories not included as separate indices. These include
outlets, travel hub locations, and free-standing locations such
as garden centres.
